MONEYJOURNEY RESEARCH
MercadoLibre Inc (MELI)
QUALITY VALUE INVESTING RESEARCH
| SECTOR Consumer Cyclical — Internet Retail |
PRICE AT ANALYSIS $1537.84 |
MARKET CAP $78.03B |
DATE November 9, 2026 |
| FAIR VALUE $1849.40 |
MARGIN OF SAFETY 16.8% |
QUALITY SCORE 81.6 / 100 |
SIGNAL Buy |
| TL;DR — EXECUTIVE SUMMARY Verdict — Buy — shares trade at $1537.84 against a probability-weighted fair value of $1849.40, a margin of safety of 16.8% and an expected annual return of 19.2%. Business quality — MercadoLibre is an exceptional Latin American e-commerce and fintech leader (Quality Score 81.6/100) delivering 33.3% growth and an outstanding 11.4% FCF yield. Key risk — Investors should monitor regional credit quality while leveraging the current Buy signal and 16.8% margin of safety to build a long-term position. |
01 — MoneyJourney Introduction
This report follows the MoneyJourney quality value investing framework: understand the business first, assess its quality and durability, calculate a reasoned estimate of intrinsic value, and only act with a margin of safety. The goal is a repeatable, transparent process — not a prediction.
A quality-focused value investor might re-evaluate MercadoLibre as its rapid growth converges with strong cash generation, creating an entry opportunity in a business with secular competitive advantages across Latin America.
02 — The Business
What They Do & How They Make Money
MercadoLibre is Latin America’s premier e-commerce and fintech ecosystem, operating across 18 countries with key markets in Brazil, Mexico, and Argentina. The company operates through two primary segments: Commerce and Fintech. The Commerce division operates an online marketplace enabling third-party merchants and brand partners to sell goods, while also conducting first-party retail sales. This segment is supported by Mercado Envíos, a proprietary logistics and fulfillment network, and Mercado Ads, a digital advertising platform. The Fintech division, Mercado Pago, originally built to facilitate marketplace transactions, has expanded into a full-scale digital financial services ecosystem. Mercado Pago provides payment processing for online and offline merchants, digital wallet services, consumer asset management, and credit underwriting through Mercado Crédito. Mercado Crédito provides working capital loans to merchants and consumer credit options at checkout. Together, these segments form a self-reinforcing flywheel where commerce traffic feeds payments and credit adoption, which in turn fuels transaction volume.
Competitive Landscape
MercadoLibre competes primarily against Amazon and Sea Limited (Shopee) in regional e-commerce, as well as digital banks like Nubank in financial services. Against Amazon, MercadoLibre holds superior localized logistics infrastructure and higher merchant penetration in key Latin American markets, maintaining its market leadership position. Against Sea Limited, MercadoLibre competes on delivery speed and product selection, leveraging its integrated payment and credit network to defend consumer loyalty. In fintech, Mercado Pago faces intense competition from Nubank, but maintains a unique advantage through direct integration into merchant checkout flows. Overall, MercadoLibre’s competitive position remains strong and is actively strengthening due to its unified marketplace and financial flywheel.
PEER COMPARISON
| COMPANY | OPERATING MARGIN | ROIC |
| MercadoLibre Inc (MELI) | 7.4% | 13.0% |
| Amazon.com Inc (AMZN) | 6.4% | 9.8% |
| Sea Ltd (SE) | 3.2% | 5.5% |
| Nu Holdings Ltd (NU) | 32.5% | 18.5% |
Revenue Breakdown
BY SEGMENT
Commerce revenue accounts for roughly 55% to 60% of total revenue, while Fintech (Mercado Pago) represents approximately 40% to 45%.
BY GEOGRAPHY
Brazil generates roughly 50% to 55% of total revenue, Mexico accounts for approximately 20% to 25%, and Argentina contributes roughly 15% to 20%.
Competitive Advantages & Moat
- Brand Strength — Strong regional brand recognition as the trusted pioneer for e-commerce and digital payments across Latin America.
- Network Effects — Powerful two-sided network effects where a growing shopper base attracts more third-party merchants and fintech adoption.
- Switching Costs — Moderate switching costs within Mercado Pago as merchants integrate payment software, point-of-sale hardware, and credit facilities.
- Cost Advantages / Scale — Significant cost advantage built on a widespread, localized fulfillment and delivery network (Mercado Envíos).
- Regulatory / IP Protection — Limited
Risk Factors
- Deterioration of credit performance within Mercado Crédito leading to rising bad-debt provisions during regional economic downturns.
- Foreign exchange devaluations and macroeconomic volatility across key operating markets like Argentina and Brazil.
- Intense competition from global e-commerce players like Amazon and digital banking platforms like Nubank.
Bull Case
MercadoLibre continues to consolidate market share in Latin American e-commerce and fintech, leveraging its superior fulfillment infrastructure and integrated ecosystem. Expanding credit and advertising offerings provide high-margin revenue streams that can expand operating margins. The current forward P/E of 28.9x and strong FCF yield offer an attractive entry point toward the $2750.56 bull valuation scenario.
Bear Case
Expanding the credit portfolio increases balance sheet exposure to consumer default cycles during macroeconomic headwinds in Latin America. persistent currency depreciation could continually dilute top-line revenue growth when translated into USD. Competitive price pressure from aggressive entrants could compress marketplace commissions and profit margins.
03 — Fundamentals
Valuation Multiples
| Market Cap ($B) | 78.03 |
| Enterprise Value ($B) | 77.88 |
| EV / EBITDA | 19.8x |
| P/E | 41.3x |
| Forward P/E | 28.9x |
| Forward Earnings Yield | 3.5% |
| P/FCF | 8.8x |
| FCF Yield | 11.4% |
Margins & Growth
| Revenue Growth (5Y) | 37.5% |
| Sales Growth YoY | 33.3% |
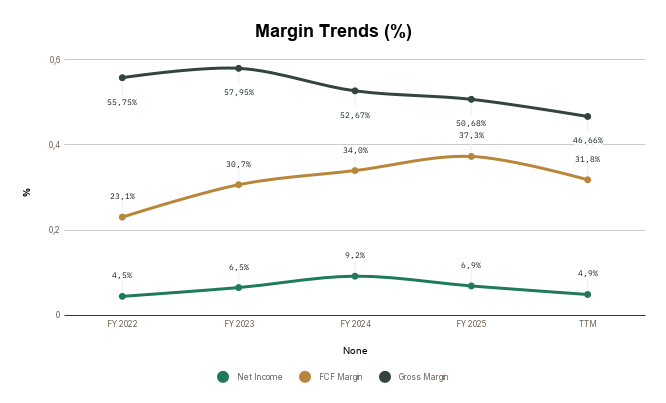
| Gross Margin | 46.7% |
| Operating Margin | 7.4% |
| Net Margin | 4.9% |
Balance Sheet & Returns
| Cash ($M) | 7398 |
| Long-Term Debt ($M) | 6216 |
| Net Cash ($M) | 1182 |
| Years to Pay Debt | -0.6 |
| ROE | 26.2% |
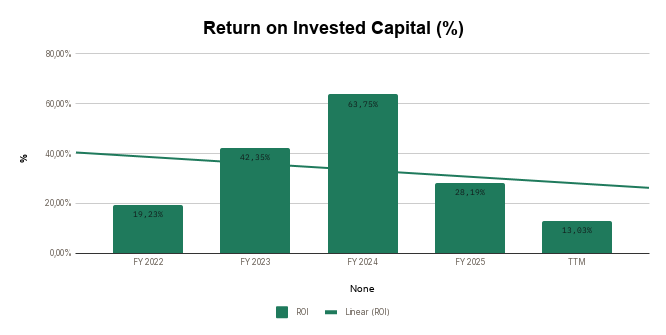
| ROIC | 13.0% |
| 5-Yr Avg ROIC | 33.3% |
Capital Returns
| Dividend Yield | —% |
| Payout Ratio | 0.00% |
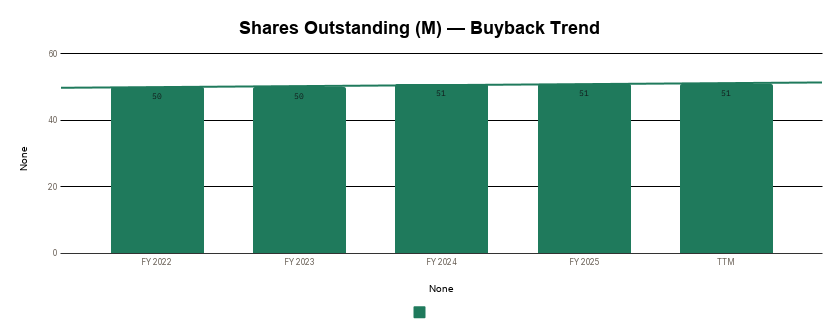
| Buybacks (Share Count Δ) | 0.5% |
| Avg. Distribution Yield | 0.0% |
What the Numbers Show
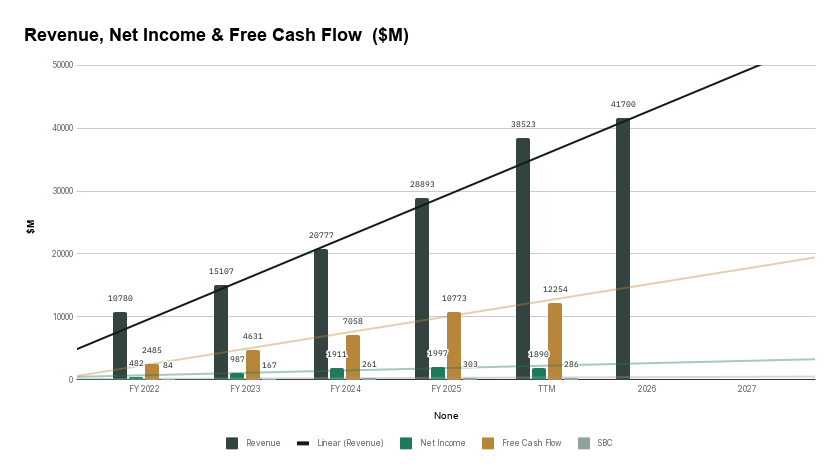
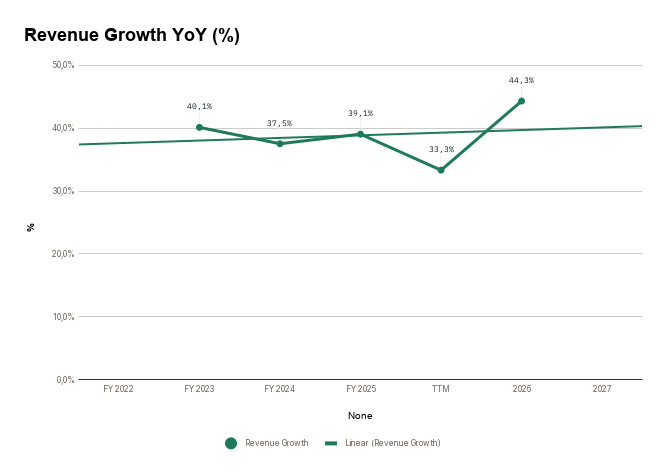
MercadoLibre demonstrates high top-line growth durability, evidenced by 33.3% YoY sales growth and a 5-year CAGR of 37.5%. Operating margin (7.4%) and net margin (4.9%) reflect intentional reinvestment into logistics infrastructure, digital advertising, and credit loss provisioning. Capital efficiency remains respectable with an ROE of 26.2% and ROIC of 13.0%, down from its 5-year average of 33.3% as the company expands its credit loan book on the balance sheet. Outstanding cash conversion is highlighted by an 11.4% FCF yield, while balance sheet strength is solid with $1.18B in net cash.
5-Year Trend — Charts
Revenue, Net Income & Free Cash Flow ($M)
Revenue Growth YoY (%)
Margin Trends (%)
Return on Invested Capital (%)
Net Income/Share & FCF per Share ($)
Shares Outstanding (M) — Buyback Trend
04 — Quality Scorecard
| CRITERION | VALUE / ASSESSMENT | PASS |
| Revenue Growth | 37,5% | ✔ |
| Market Potential / Industry Growth | 23,45% | ✔ |
| Quality of Revenues | Consumer Based | Medium |
| Product / Process Development | Yes | Better |
| Research & Development | — | Better |
| High Gross Margins | 52,7% | ✔ |
| Profit Margins | 6,4% | ✔ |
| Maintaining Profit Margins | Yes | ✔ |
| Margins vs. Competition | — | Better |
| Pricing Power | Yes | ✔ |
| Debt Structure | -0,63 | Better |
| Rates of Return (ROIC / ROE) | 33,3% | ✔ |
| Management Depth | — | Very competent |
| Culture, Reputation & Labor Relations | — | Good |
| MOAT / Competitive Advantage | Network Effect | Wide / Formidable |
| MOAT Trend | — | Enduring |
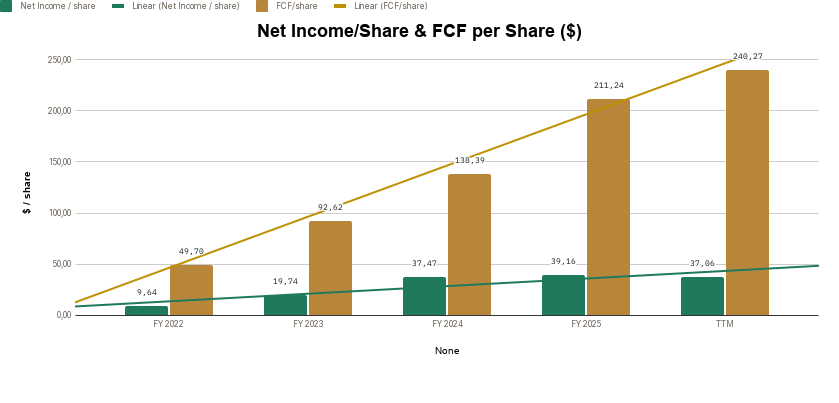
| FCF / Share Growth | 50,5% | ✔ |
| Returns Capital (Dividends/Buybacks) | 0,0% | ✔ |
| QUALITY SCORE | — | 81.6 / 100 |
Scale: 80-100 Exceptional · 60-79 Strong · 40-59 Mixed · Below 40 Weak.
What’s Driving the Score
The score is anchored by strong marks on Rates of Return (ROIC / ROE) (10%), Pricing Power (8%), and FCF / Share Growth (8%) — three of its most heavily weighted criteria. Together, the criteria with a clear pass or fail account for roughly 45% of the total weighting — the rest sit at a middling score rather than a firm strength or weakness.
05 — Valuation
Key Assumptions
| Country | Uruguay |
| Business Risk | Low |
| Discount Rate | 15.98% |
| Revenue Growth — Base | 15.0% |
| Revenue Growth — Bull | 18.0% |
| Revenue Growth — Bear | 12.0% |
| FCF Margin (2032E) | 12.0% |
| Exit P/E Multiple (Base) | 20.0x |
Scenario Analysis
| CASE | PROB. | REV. GROWTH | EXIT P/E | INTRINSIC VALUE |
| Base Case | 60% | 15.0% | 20.0x | $1808.93 |
| Bull Case | 20% | 18.0% | 22.0x | $2750.56 |
| Bear Case | 20% | 12.0% | 18.0x | $953.16 |
Probability-Weighted Fair Value
| FAIR VALUE $1849.40 |
NET CASH / SHARE $23.30 |
MARGIN OF SAFETY 16.8% |
EXPECTED ANN. RETURN 19.2% |
What This Means
With a Fair Value of $1849.40 against a current price of $1537.84, the stock offers a 16.8% Margin of Safety and an expected annual return of 19.2%. The valuation scenario spans from a Bear case of $953.16 to a Bull case of $2750.56, suggesting that the current forward P/E of 28.9x provides attractive upside for long-term compounders.
Sensitivity Analysis
Intrinsic Value ($ / share) — Discount Rate × Exit P/E
| DISC. RATE ↓ / EXIT P/E → | 16x | 20x | 24x |
| 15.0% | 1524.31 | 1905.39 | 2286.47 |
| 16.0% | 1447.14 | 1808.93 | 2170.71 |
| 17.0% | 1374.49 | 1718.11 | 2061.73 |
Intrinsic Value ($ / share) — Revenue CAGR × FCF Margin
| REV. CAGR ↓ / FCF MARGIN → | 10.0% | 12.0% | 14.0% |
| 14.0% | 1416.85 | 1713.25 | 2009.65 |
| 15.0% | 1496.58 | 1808.93 | 2121.27 |
| 16.0% | 1579.85 | 1908.85 | 2237.86 |
06 — My Take
Overall Conclusion
MercadoLibre is an exceptional business (Quality Score 81.6/100) anchored by dominant regional scale, structural network effects, and robust equity returns. The valuation presents a clear Buy signal supported by a 16.8% Margin of Safety and an 11.4% FCF yield. The primary risk to the thesis is credit asset quality deterioration within Mercado Crédito alongside Latin American macroeconomic and currency volatility. Long-term investors are presented with a high-quality platform compounder trading at a reasonable price relative to its growth capabilities.
Investment Thesis Check
☒ Is it cheap? (Margin of safety at current price)
☑ Is it a good business? (Quality Score reflects durable fundamentals)
☑ Who is running it? (Management track record checked)
What did I miss? (Deliberately looked for the counter-argument)
3 Sources of Returns
☑ Revenue / Earnings Growth
☒ P/E Expansion
☒ Buybacks and Dividends
| VERDICT BUY |
Entry Execution & Support Levels
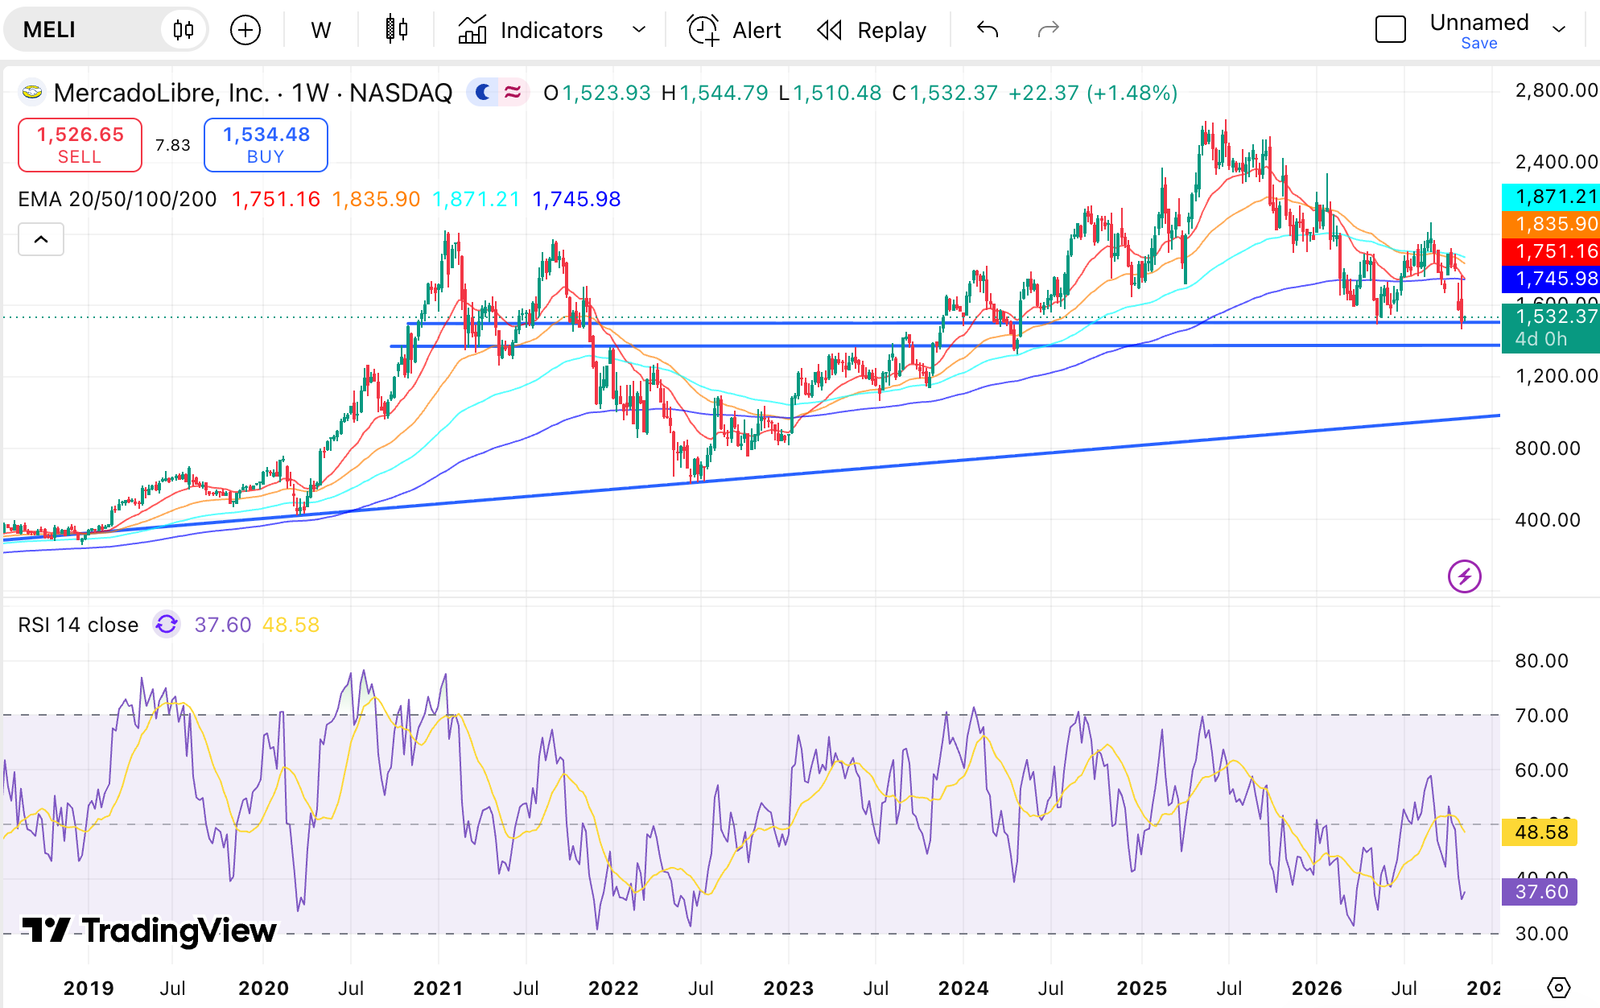
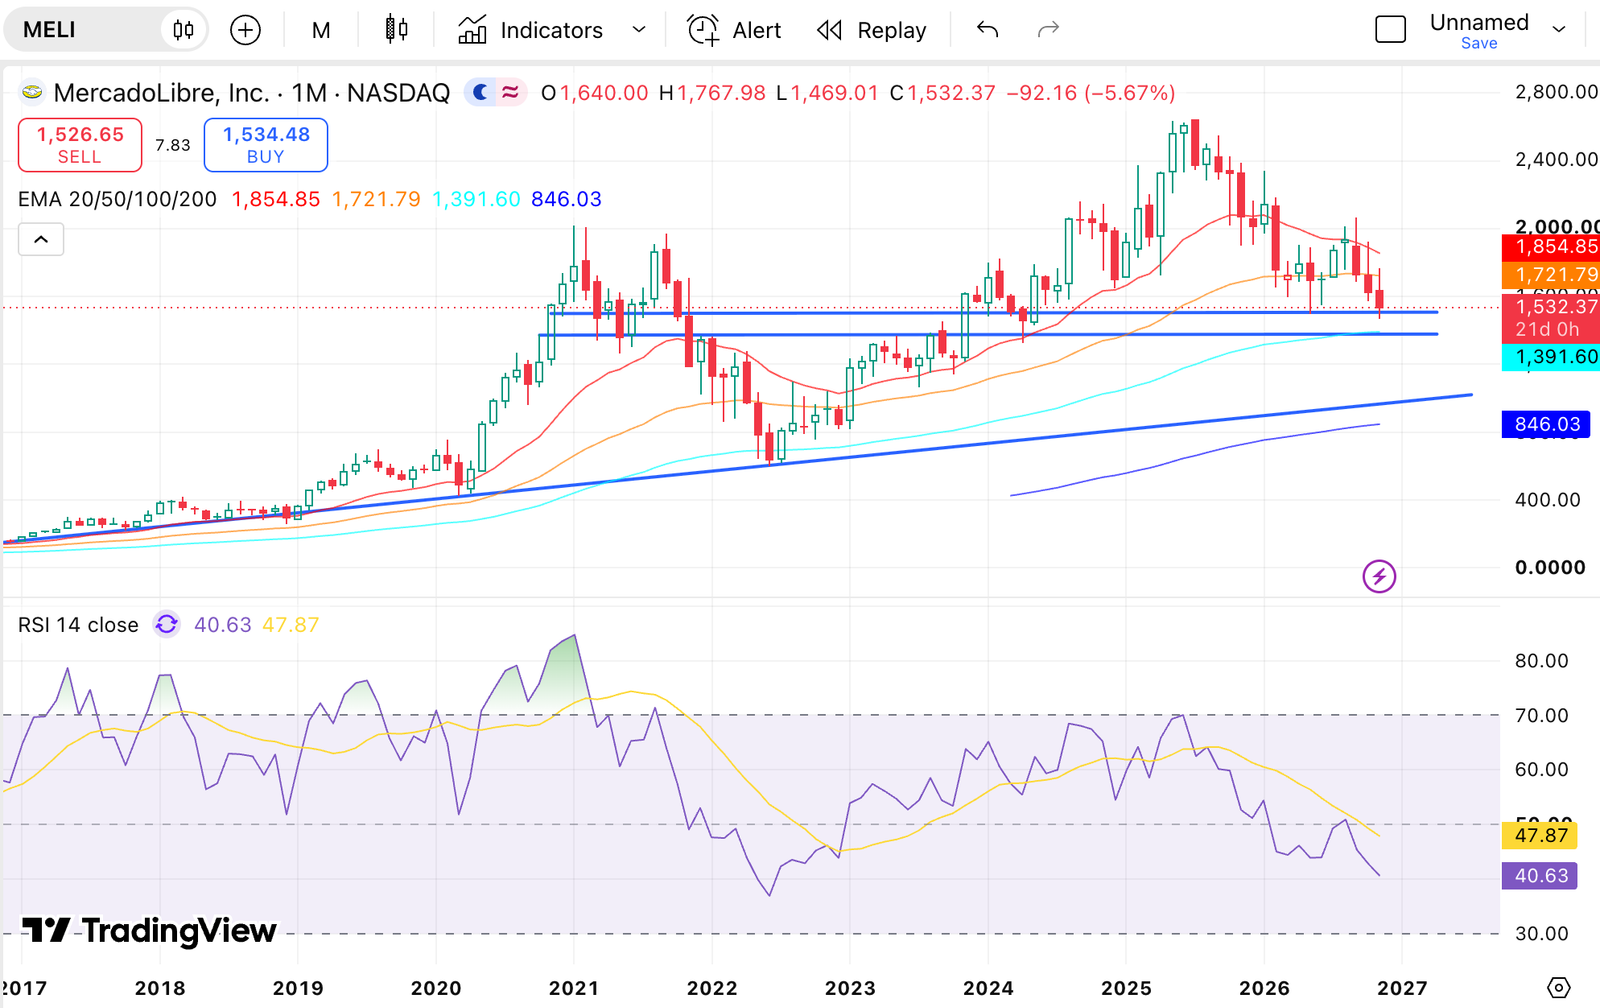
Weekly and Monthly timeframe, shows good support between 1500$ to 1400$. I like this level for a starting position. MELI is a great company, at an attractive valuation. I will redo my due diligence and evaluate if 1400$ is a good entry point to start a position.